Start with an invoice, not a token
A company can agree a sale immediately and still wait for the money to reach its supplier. OSL addresses the operations between that agreement and a usable balance: receiving funds, converting currencies or digital assets, moving value across a supported network, paying a beneficiary and reconciling the result. Its mission frames money movement as an information problem. Signet reads the company as a provider that wants to make stablecoins useful inside financial operations, with bank connectivity, liquidity and account controls attached to the transfer.
Consider an illustrative marketplace paying an overseas seller. The operations team starts with an approved payment instruction and the finance team decides the required destination currency. Before a transfer, the serving entity, merchant eligibility, beneficiary information and permissible route are agreed. A platform integration can bring the instruction into an approved payment workflow, but the commercial customer still owns its own user relationship and business purpose. These boundaries explain why an apparently simple payment requires coordination between sales, finance, compliance and engineering.
Conversion and settlement are separate jobs
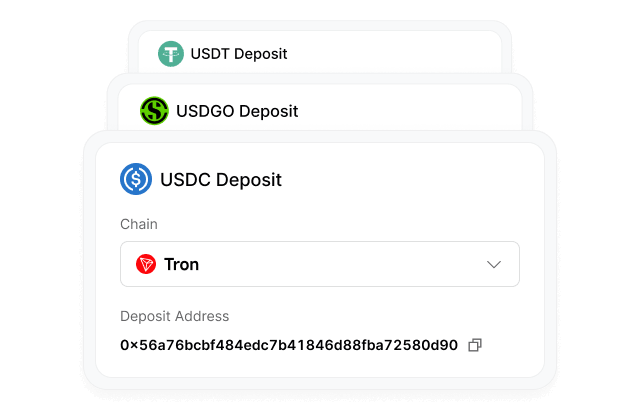
The funding leg can use a supported fiat account or a stablecoin balance. OSL Business Account provides a view of eligible balances, while Markets provides institutional conversion through negotiated dealing or a request for quote. A quote has an asset, an amount and settlement conditions; a treasury team must decide whether those terms fit its obligation. BizPay then connects the selected conversion and payment route. A blockchain leg can run beyond ordinary bank hours, while the destination bank, local partner and compliance checks still influence final delivery.
The operating result is more than an on-chain transaction identifier. A finance team needs to match the payer, invoice, conversion, recipient and final balance. Named account references can help attribute incoming funds. Permissions and multi-person approval can separate the person who prepares an instruction from the person who approves it. Exceptions also matter: a delayed payout, a wrong beneficiary detail or a returned bank payment needs an owner. Signet would evaluate the infrastructure through these completed financial tasks rather than a speed claim on its own.
Keep the commercial record attached
A September 2026 implementation with Payment Asia and Anchorpoint makes the workflow tangible. Payment Asia used HKDAP for completed logistics services with ShipAny and eligible hospitality services booked through Flow. Anchorpoint handled issuance and redemption; OSL supplied distribution and settlement infrastructure. The announcement follows funding, minting, payment, same-day reconciliation, redemption and token destruction. The case shows how a digital settlement asset can stay connected to commercial records. It is evidence of that described implementation, with its partners and eligible activities, rather than a guarantee for every corridor.
For a Korean reader, the useful starting question is which corporate obligation needs this chain of work. A Korean financial group may operate through a Hong Kong subsidiary; a marketplace may need a permitted overseas seller payout; a treasury team may need to reconcile multiple assets. Each situation has a different customer, contract and control boundary. Signet suggests drawing the full flow of money and records, then marking who approves, executes, holds assets and resolves an exception. That diagram makes both the product value and the human judgement easier to explain.